The Bank Was Built to Hold the Account. What If It Also Powered the Business?
Table of Contents[ 4 ]
Banking and commerce have always been connected Closing the gap The bank becomes part of the workflow The next generation of banking infrastructureFinancial institutions have spent decades becoming excellent at moving and storing money.
But merchants don’t only need money infrastructure. They need business infrastructure. They need systems that help them sell.
That creates a new question for banking: what happens when the institution that holds the merchant’s money also provides the infrastructure behind the merchant’s business?
Banking and commerce have always been connected
A business needs an account because it has a business. It receives money because it sells. It needs payments because customers buy. It may need credit because it wants to grow.
The relationship between finance and commerce is therefore not artificial. Commerce generates the activity that financial services respond to.
Yet the software powering commerce has largely developed outside the bank.
Closing the gap
Commerce infrastructure gives institutions a way to close that gap. A bank can provide:
- The account. Where money lives.
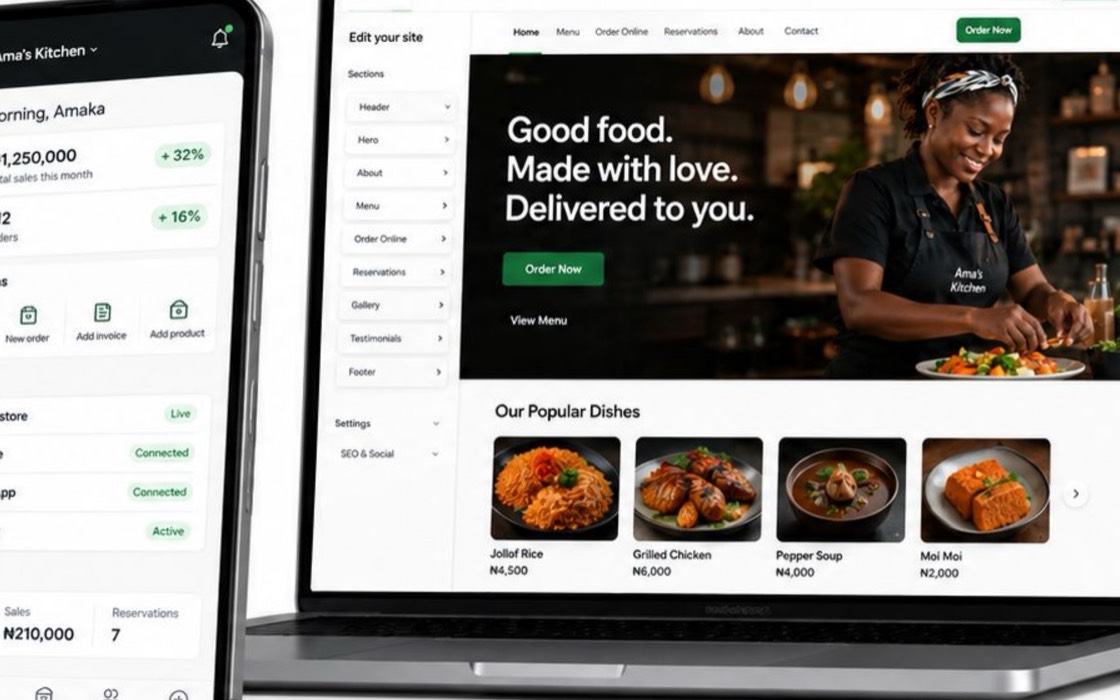
- The commerce layer. Where the business operates.
- The payment infrastructure. Where transactions happen.
- The financial products. Built around the activity generated by the business.
That creates a much more complete merchant relationship.
The bank becomes part of the workflow
The strategic shift is subtle. The bank isn’t merely adding another feature. It is becoming part of the merchant’s daily workflow.
That creates a different kind of relationship. The merchant isn’t only checking their balance. They’re running their business. And the institution is underneath that activity.
The next generation of banking infrastructure
The future of banking won’t necessarily be about adding more tabs to a banking application. It may be about expanding the infrastructure underneath the businesses banks already serve.
Commerce is one of the largest layers still sitting outside the traditional banking stack. Bringing it inside changes what a financial institution can build.
The bank account was the beginning. It doesn’t have to be the boundary.