The Commerce Layer Is Becoming Financial Infrastructure
Table of Contents[ 5 ]
Commerce has become software The missing layer From financial relationship to commerce relationship Infrastructure changes the economics The next generation of financial institutionsThe bank account was never the whole merchant relationship.
For decades, the relationship between a financial institution and a business has been organised around one fundamental object: the account.
A merchant opens an account. Money comes in. Money goes out. Payments settle. Financing is provided. Statements are generated.
But the business itself happens somewhere else.
A merchant chooses products, creates a website, receives orders, accepts payments, manages customers, tracks inventory, runs a physical location and communicates with buyers through a collection of systems that may have little connection to the institution holding its money.
The financial institution sees the transaction. It doesn’t necessarily power the commerce behind it.
That distinction is becoming increasingly important.
Commerce has become software
A modern merchant does not simply receive payments. They operate a software-defined business.
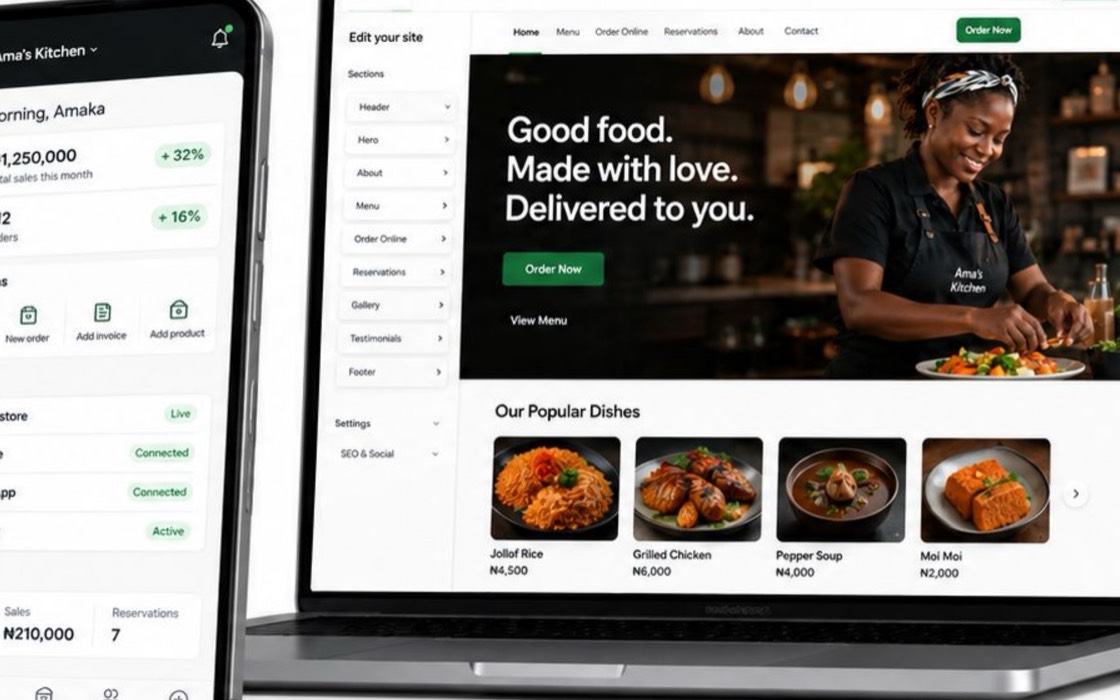
Their commerce stack might include a website, a checkout, a point-of-sale system, payment links, product management, orders, customer records, inventory, discounts, loyalty, analytics, subscriptions and bookings.
Each of these surfaces creates information about the business. Together, they represent the operating layer of commerce.
Payments sit inside that system.
The opportunity for financial institutions is to move from being the place where commerce settles to becoming part of the infrastructure that makes commerce happen.
The missing layer
Banks already have something most commerce platforms spend years trying to acquire: the merchant relationship.
They know the business. They hold the account. They process or facilitate payments. They may provide lending, savings, cards, payroll or other financial products.
What they often don’t own is the software layer connecting those activities to the merchant’s everyday operation.
That creates a strange architecture. The bank owns the financial relationship. Another company owns the commerce relationship. The merchant lives between them.
Commerce infrastructure changes that equation. Instead of treating commerce as another application a bank can distribute, institutions can treat it as infrastructure that belongs inside their platform.
From financial relationship to commerce relationship
Imagine a merchant opening an account with a bank. Today, the bank might provide:
Account → Payments → Settlement
With a commerce layer, the relationship becomes:
Account → Commerce → Payments → Settlement
The merchant can create a website. Accept an order. Take a payment. Sell from a physical terminal. Send a payment link. Manage customers. Track transactions. And all of those activities can connect back to the institution that already serves the merchant.
The important change isn’t that the bank has launched another product. It is that the bank has moved closer to the actual operation of the business.
Infrastructure changes the economics
Owning more of the commerce layer creates more than a better merchant experience. It creates new infrastructure around which institutions can build products.
Commerce activity produces signals. Orders reveal demand. Transactions reveal revenue. Products reveal business categories. Customers reveal relationships. Operating activity reveals patterns.
That information can support better financial products, better merchant services and deeper relationships.
The commerce layer therefore becomes strategically interesting even when the institution isn’t trying to become a traditional commerce company. It is infrastructure for everything that comes next.
The next generation of financial institutions
The question is no longer simply: how can a bank help a merchant get paid?
How much of the infrastructure behind that merchant’s business should the bank provide?
The institutions that answer that question well will not necessarily look like commerce marketplaces. They may look like something more interesting: financial institutions with commerce infrastructure underneath them.
That is the direction Box is built for. Commerce is becoming part of financial infrastructure.